- contact@verticalserve.com
- Part of the Insight insurance suite — InsightUW · InsightCW · InsightCede · InsightPulse
InsightCW · The AI-first claims workbench
Every claim worked by agents. Every decision made by your adjusters
Ten claims agents read each claim the moment something changes — the notice, the policy at the loss date, the reserve, the documents, the clocks — reason over it with Claude, and prepare the coverage position, the reserve, the letters and the approval brief. Every figure cites the record. Nothing leaves the desk until a person with the authority accepts it.
- Every figure cited to the record
- Agents ask first by default
- Policy at the loss date from InsightUW
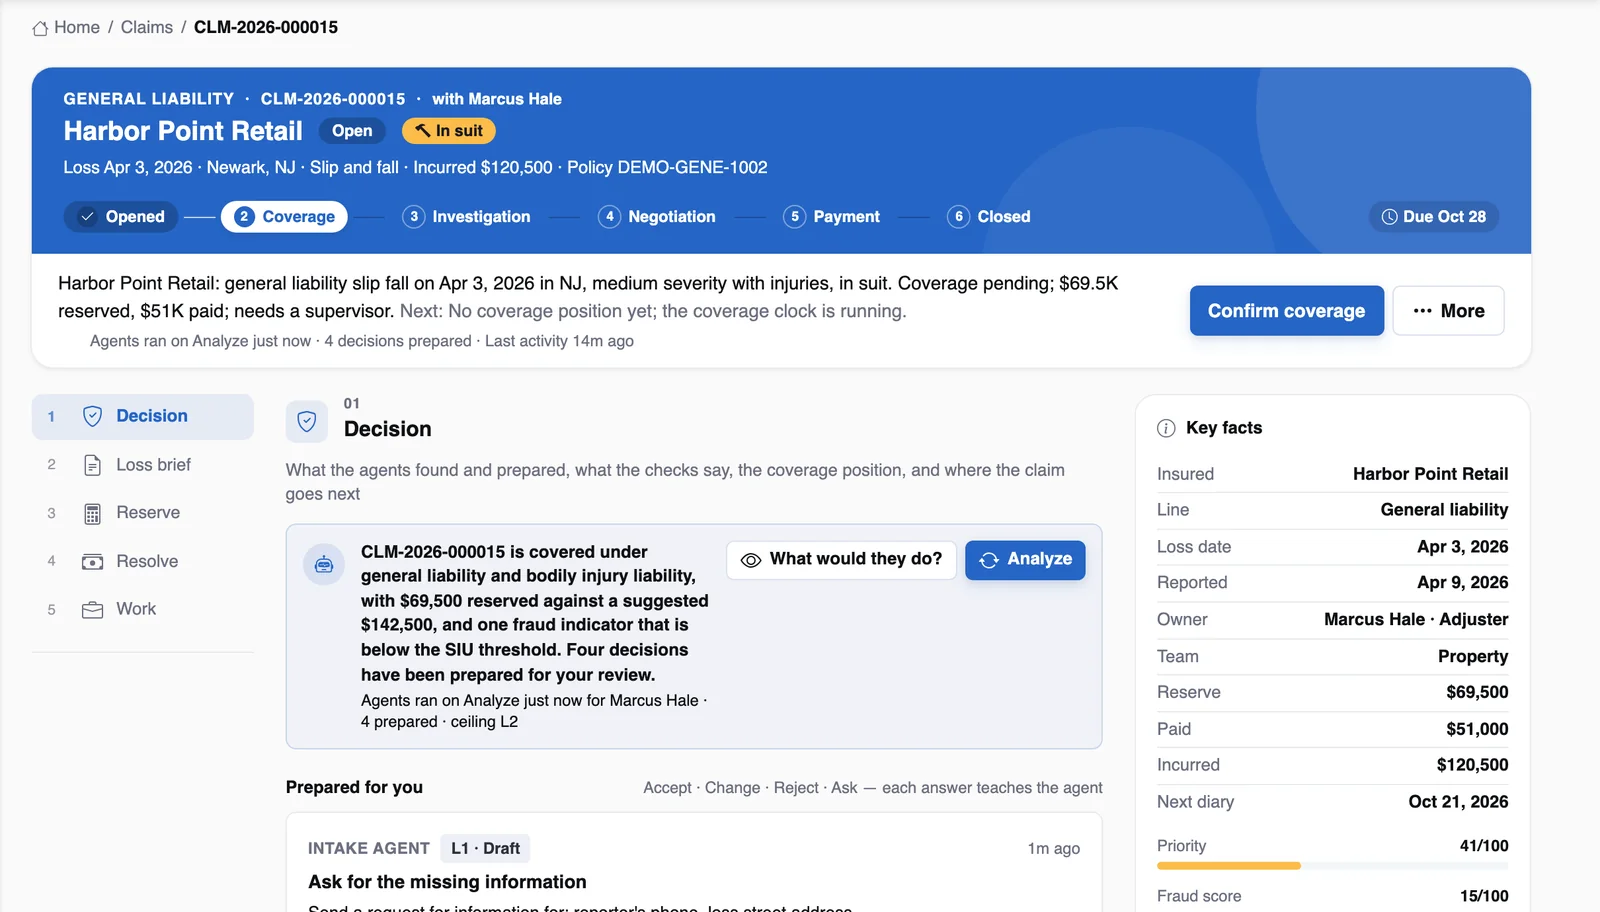
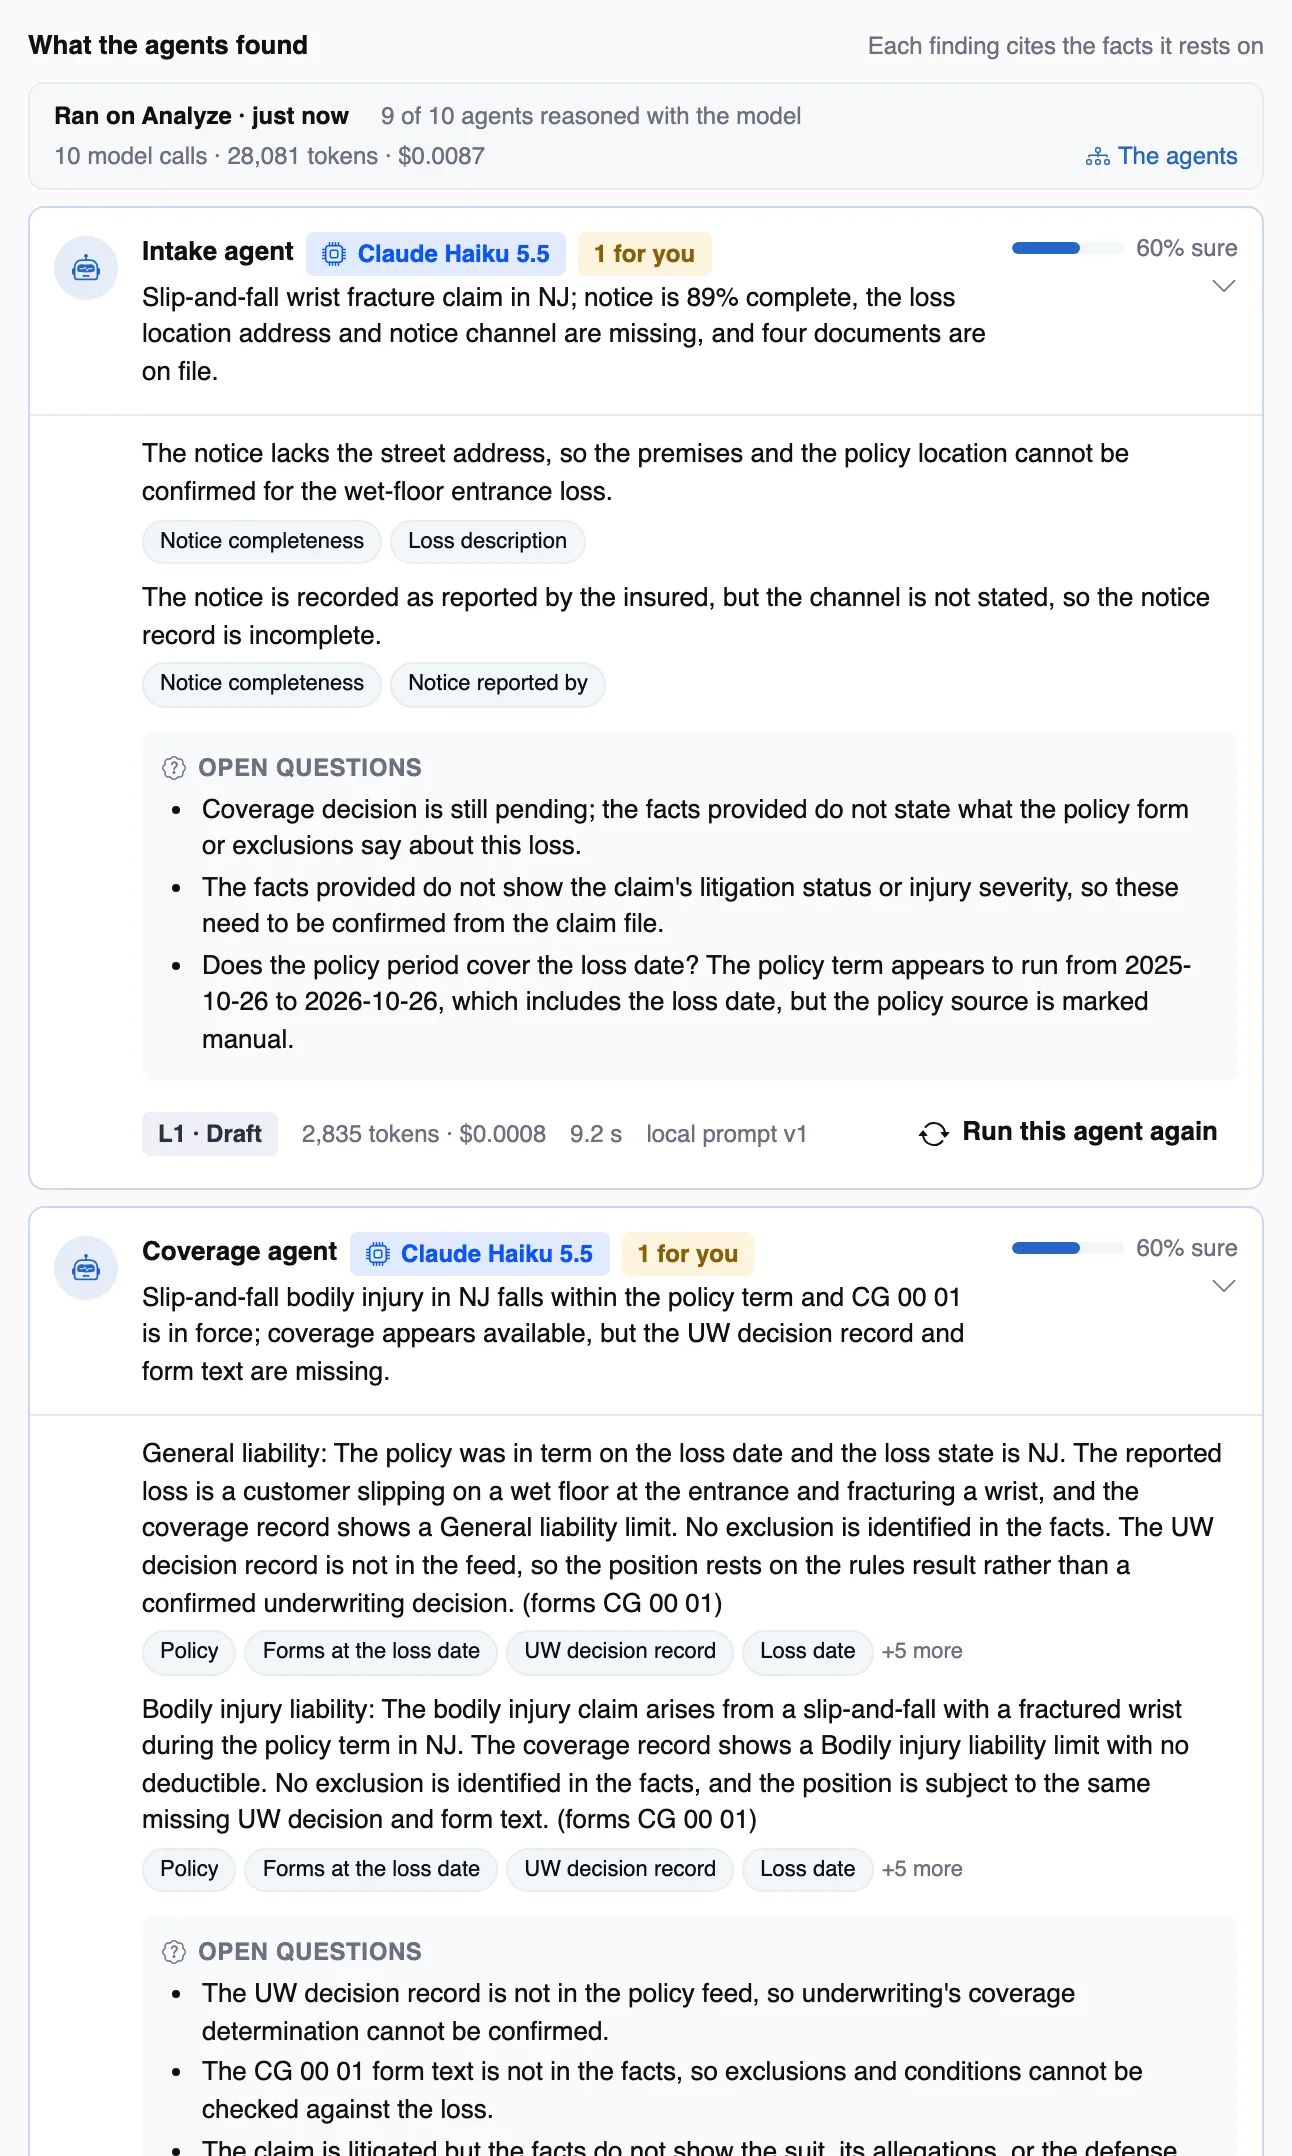
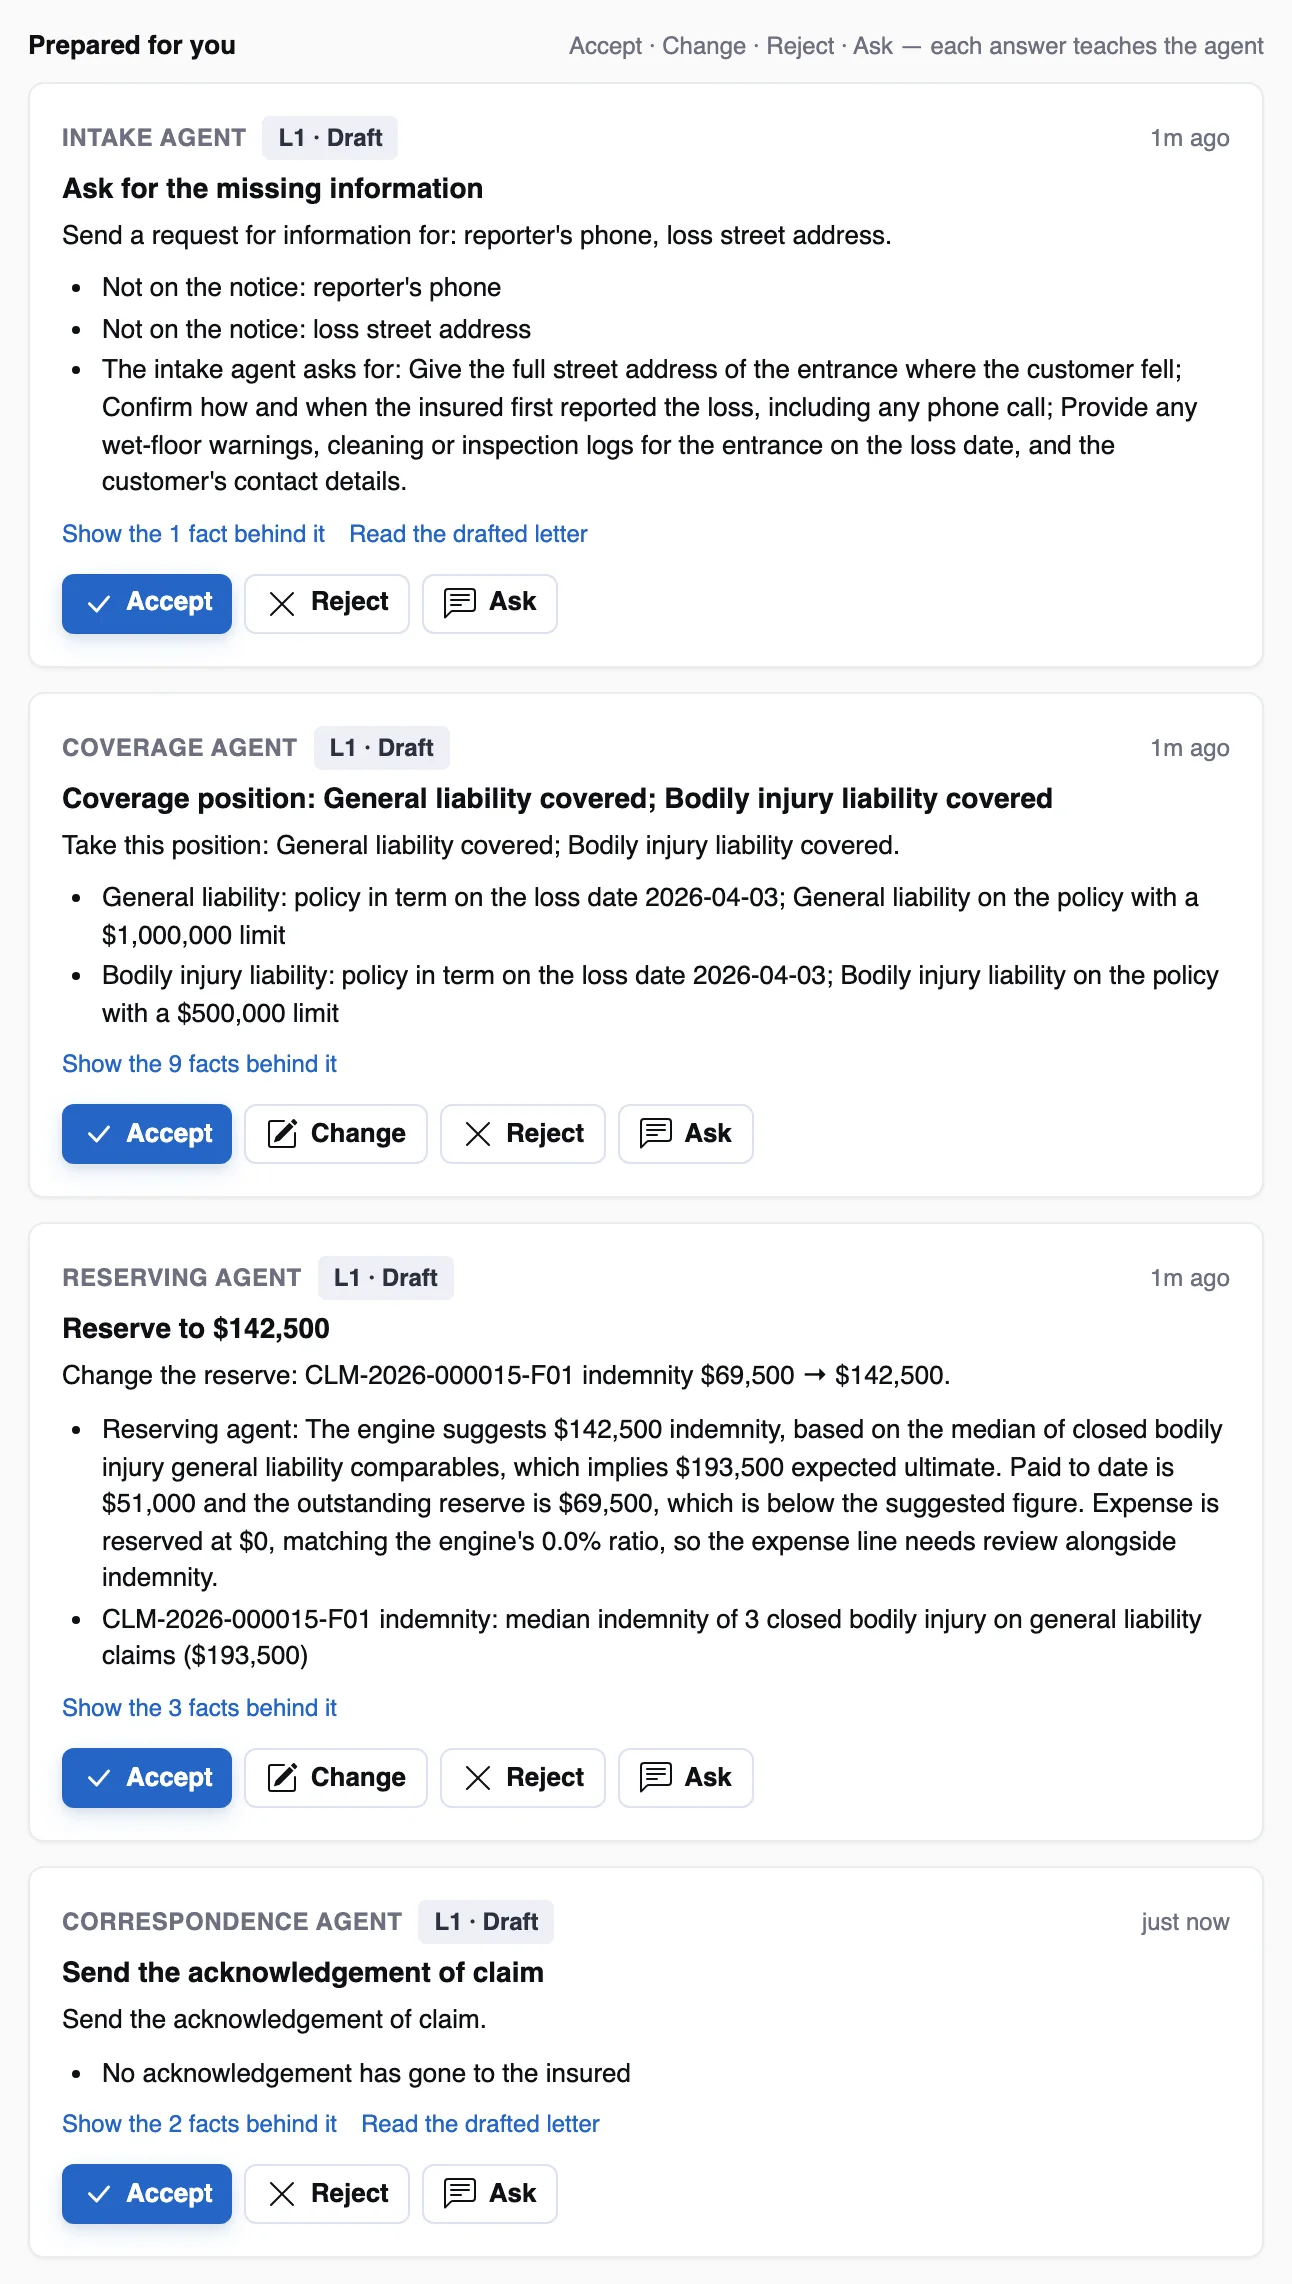
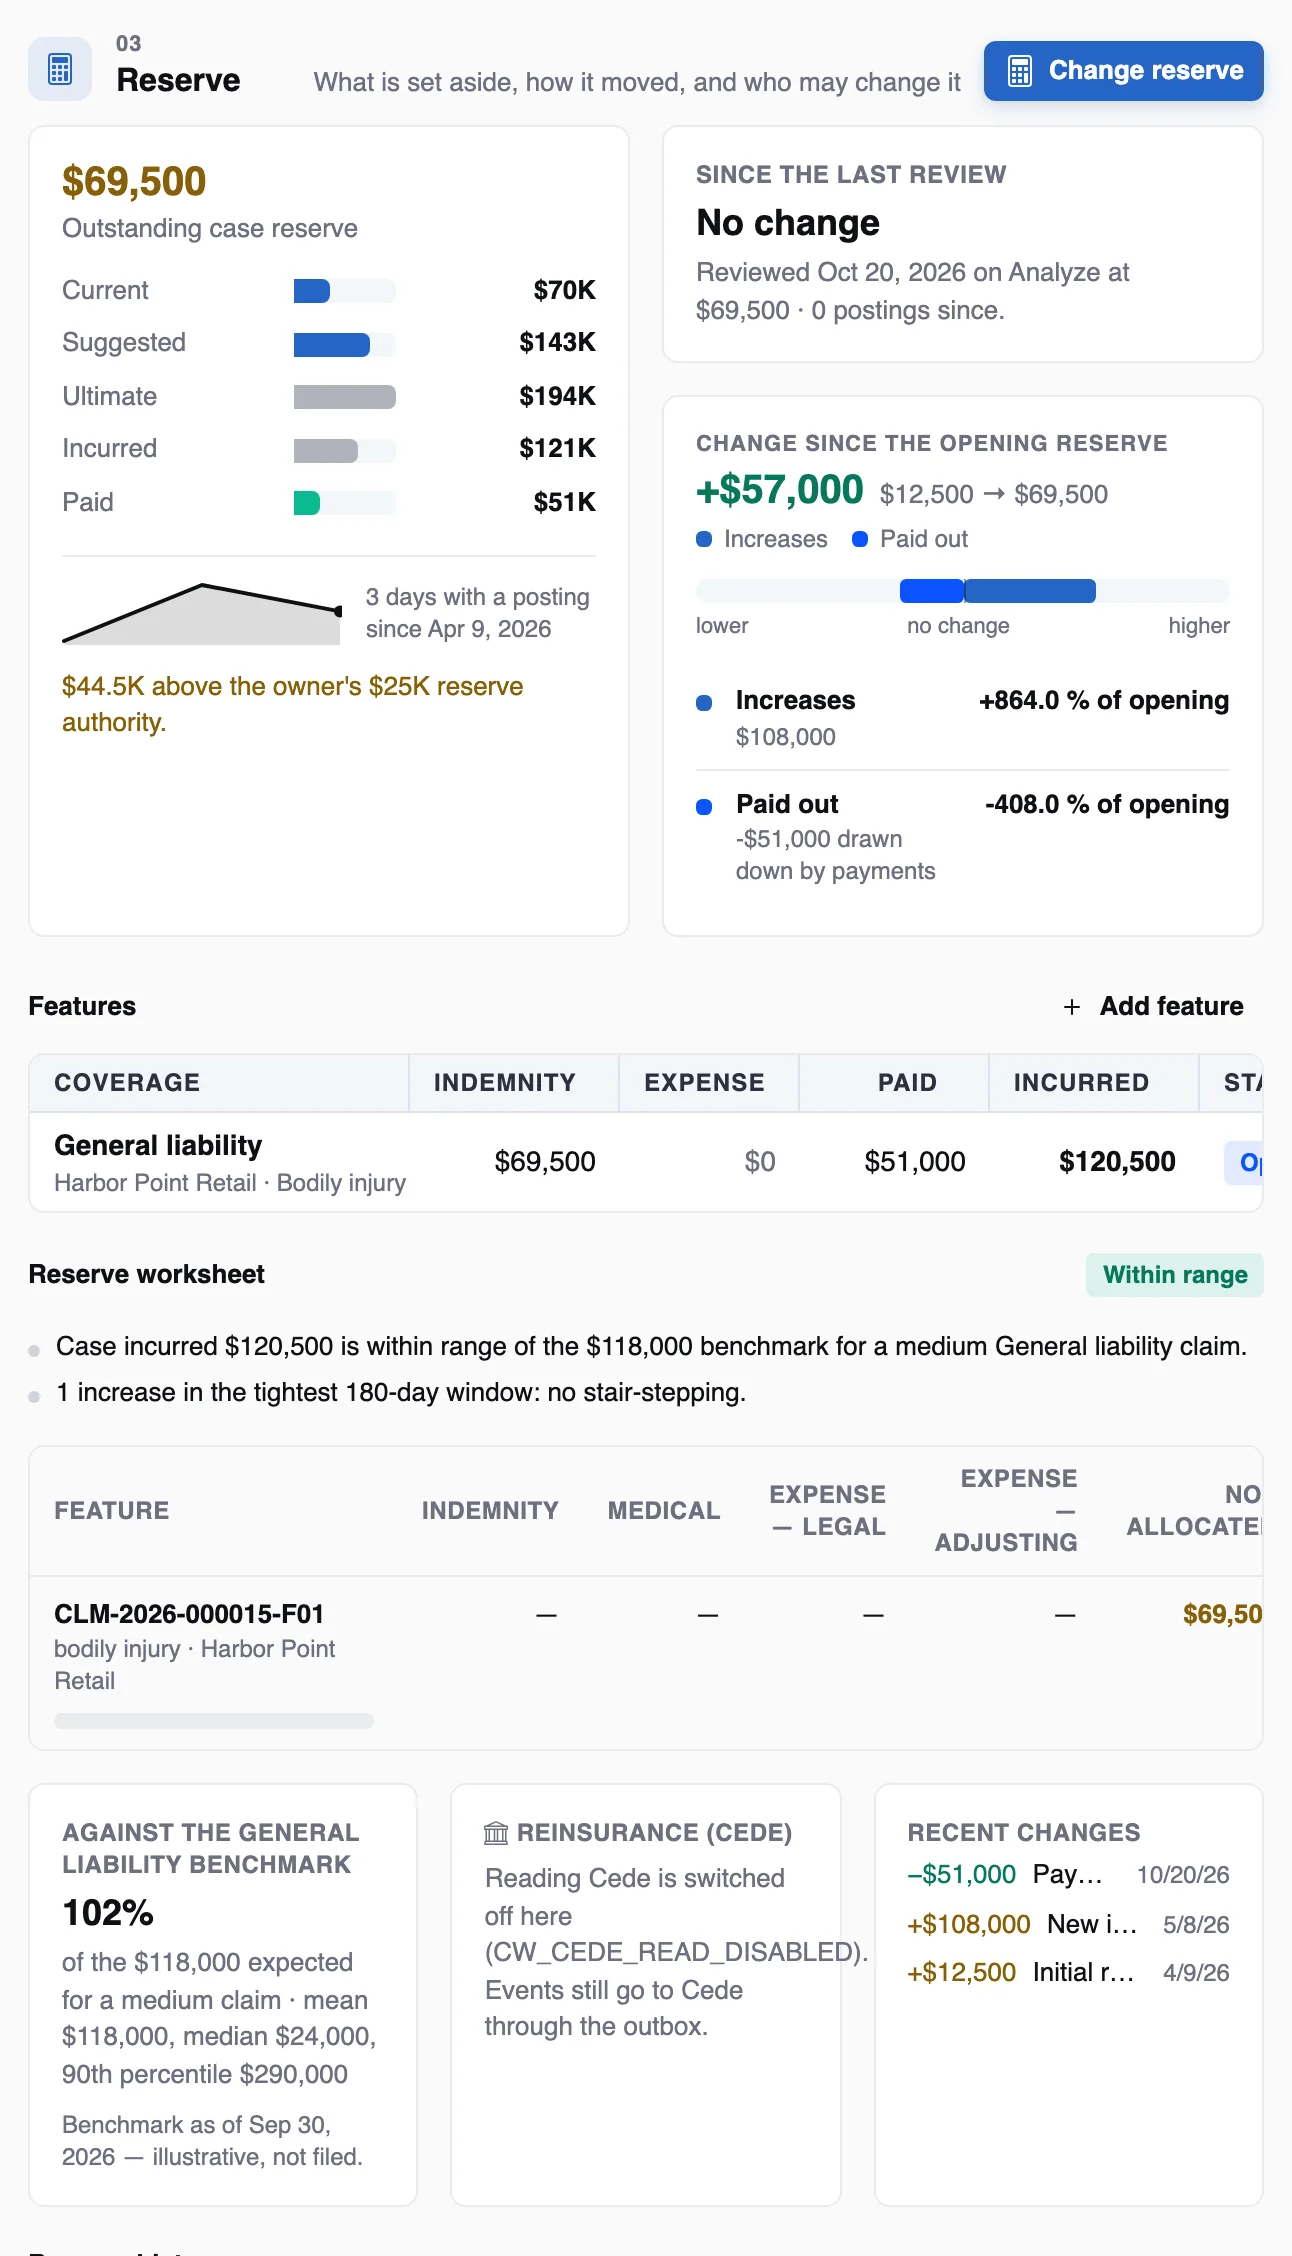
Every screen on this site is the running product on illustrative demo data. The agents’ text in them is what Claude wrote for those claims.
Line handling built in for the specialty book
Directors & officers
Errors & omissions
Employment practices
Fiduciary
Cyber
Medical malpractice
Healthcare liability
Marine & cargo
Property & CAT
Workers’ compensation
Commercial auto
General liability
The problem
A claims desk spends its day gathering, not deciding
The adjuster with forty open files rebuilds each one in their head every time it moves: what the policy said on the loss date, what the reserve rests on, which letter is due under which state’s rule, what the supervisor will ask. That is where the money and the time go.
Leakage
Reserves that walk up in steps
A reserve raised a little at a time hides the real exposure until it is late to act on it, and a recovery nobody chased is money paid twice.
Cycle time
Waiting on the next look
Coverage waits for someone to read the forms; the approval waits for someone to assemble the brief; the claim waits for both.
Adjuster load
Ten tabs per claim
Policy system, document store, payments, diary, email, the rules binder and a spreadsheet of what is owed to whom — for every file, every day.
State clocks
Deadlines nobody is watching
Acknowledge, decide, pay: each state sets its own clock on business days. A missed one is a market-conduct finding, not just a slow claim.
How it works
Something changes → the agents reason → a person decides → the record keeps it
The agents run on their own when a notice becomes a claim, a document arrives, a reserve changes, a payment is requested or a suit is filed — or when anyone presses Analyze. What they prepare waits for the person with the authority.
1
Trigger
Five events start a run automatically, debounced per claim. A dry run (“What would they do?”) shows the same work with nothing written.
2
Gather
Each agent assembles its facts from the record: the claim, the policy and forms at the loss date, reserves and payments, documents, diary, clocks, rule hits — each fact with its source.
3
Reason
Claude reasons over those facts and answers in a fixed shape, citing them by id. A number not in the facts throws the answer away; the rule-based finding stands.
4
Prepare
The agent prepares the coverage position, the reserve change, the letter, the SIU referral or the approval brief — at the level the dial allows, which out of the box is ask first.
5
Decide & learn
The adjuster accepts, changes, rejects or asks. The answer is carried out as them, written to the decision record, and counted as evidence for the agent’s level.
flowchart TD
  E["Claim event
notice converted · document · reserve · payment · suit"] --> R
  A["Analyze or dry run"] --> R
  R["Agent run: 10 agents in order"] --> G["Gather facts, each with its source"]
  G --> M["Reason with Claude
fixed JSON shape, cites the facts"]
  M --> C{"Every number
in the facts?"}
  C -- yes --> P["Findings + prepared decisions"]
  C -- no --> D["Rule-based finding stands
model answer rejected"]
  D --> P
  P --> L{"Level for this action
lowest of agent · hard cap · ceiling"}
  L -- "L1 / L2" --> H["A person: Accept · Change · Reject · Ask"]
  L -- "L3, when raised" --> T["Act and tell, with a pull-back window"]
  H --> X["Carried out as the person"]
  X --> DR[("Decision record")]
  T --> DR
  DR --> S["Agreement roll-up: recommends promotion, demotes"]
The run, as the code does it. Each agent step is recorded with its model, tokens, cost and a Lense trace.
The Claim Workspace
One page per claim, with the agents’ work on top
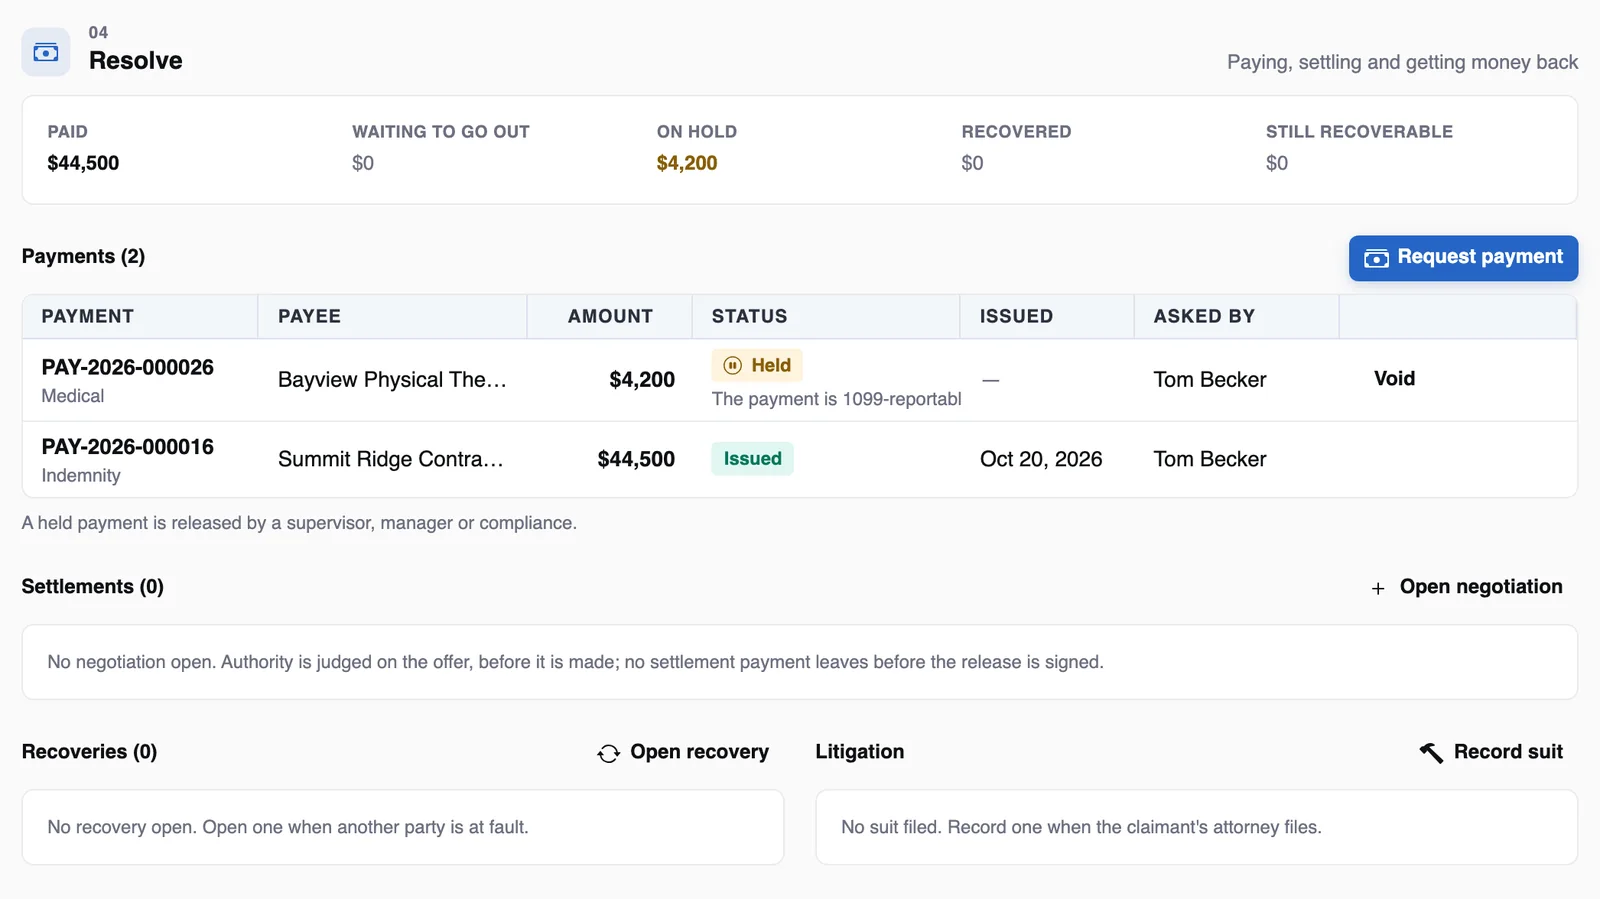
The hero says what the claim is and where it stands; the stage strip moves it through Opened, Coverage, Investigation, Negotiation, Payment and Closed. Below it, five zones — Decision, Loss brief, Reserve, Resolve and Work — hold everything the adjuster would otherwise open ten tabs for.
The agents
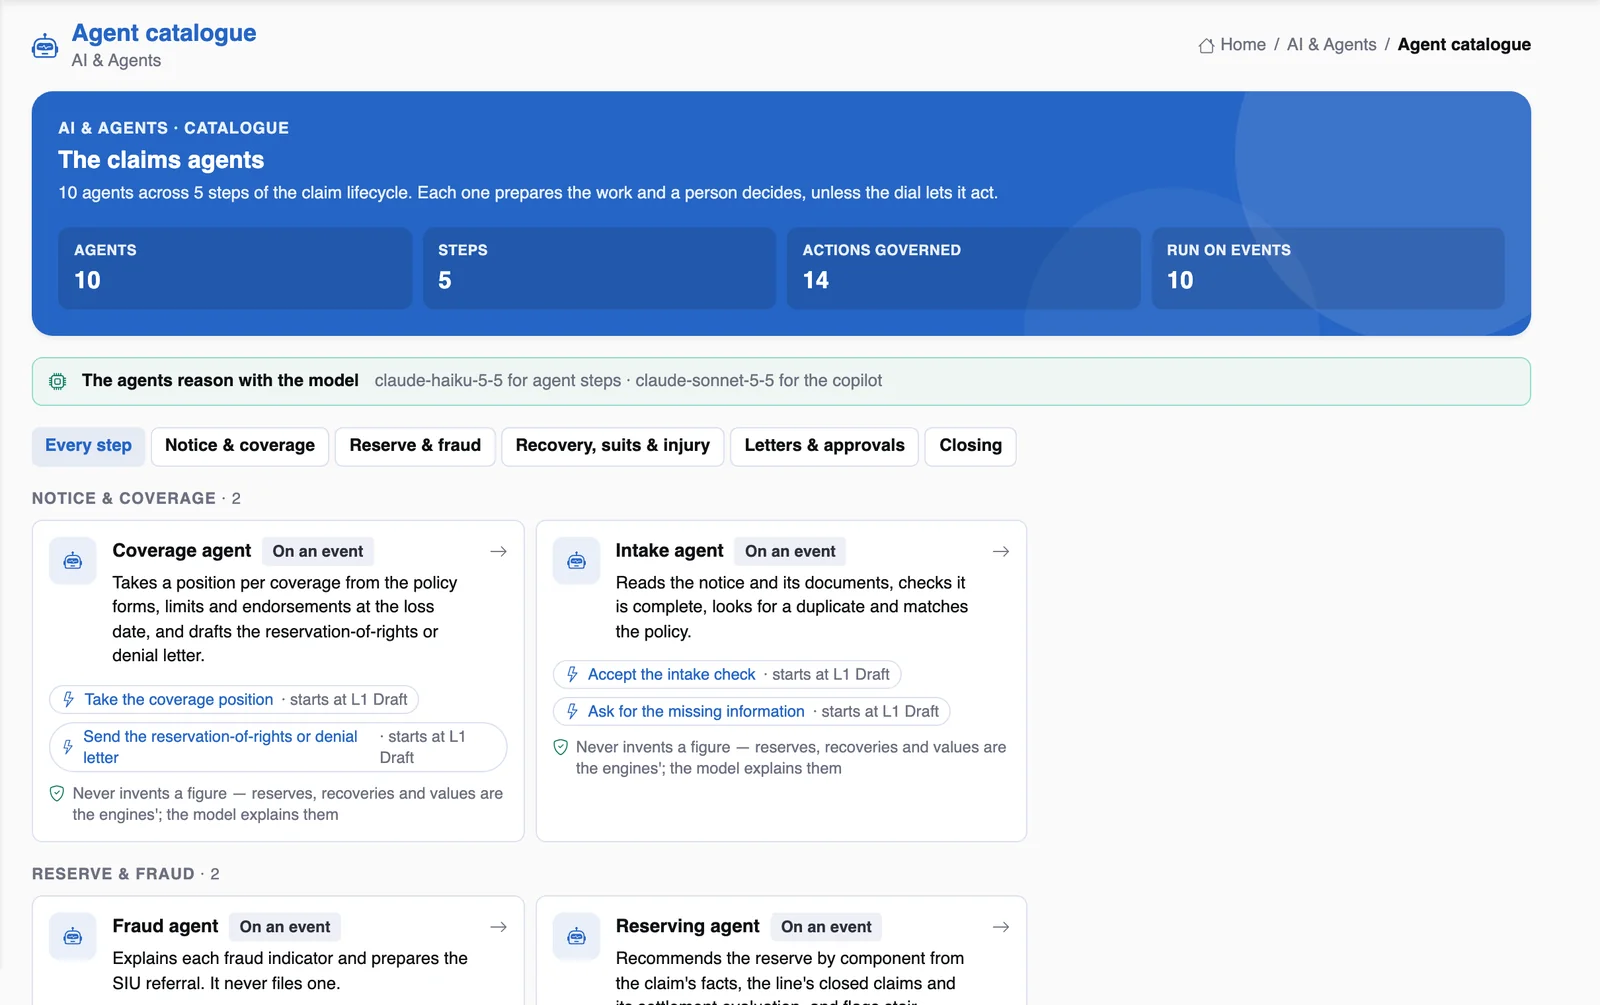
Ten claims agents, each with one job and a hard limit
Each agent keeps its rule-based findings as the facts and reasons over them with the model. Six actions are capped at ask first whatever the dial says, because a person must make them.
Intake
Completeness, contradictions, duplicates, whether the loss date falls in the term. Drafts the information request.
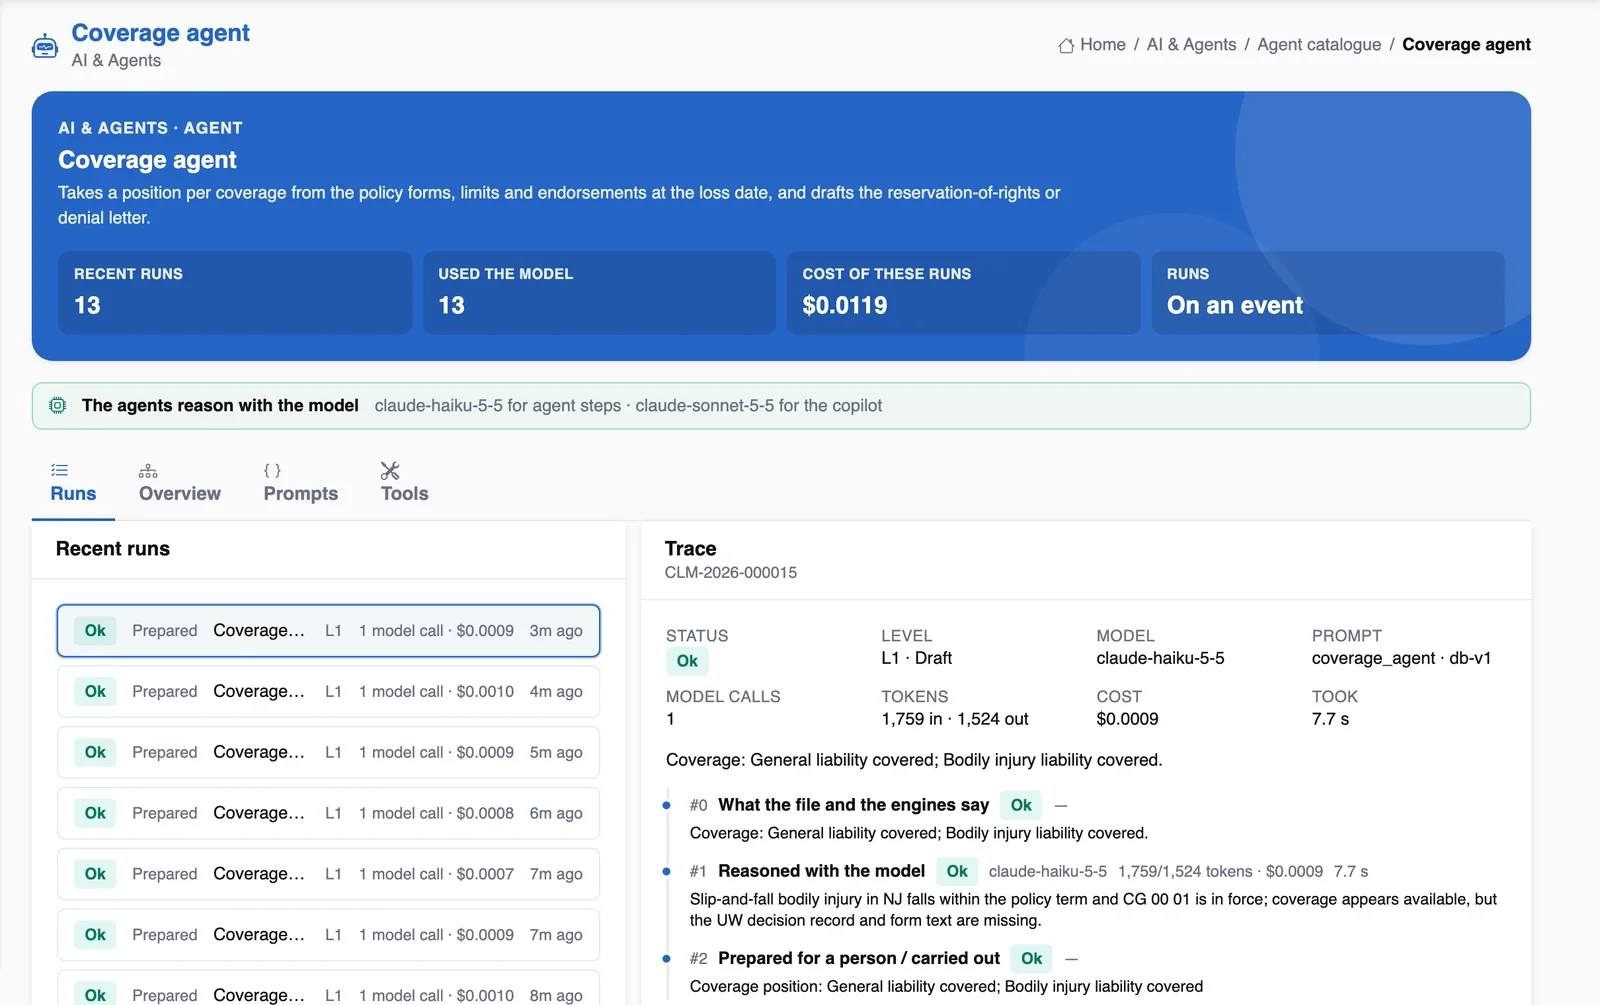
Coverage
A position per coverage from the forms and endorsements at the loss date, with confidence and open questions. Drafts the reservation of rights or denial.
Reserving
Explains the reserve, judges adequacy, challenges stair-stepping. Figures come only from the reserving methods.
Fraud
Weighs each indicator against its innocent explanations and recommends refer, monitor or no action.
Prepares SIU referrals; never filesSubrogation
Names the other side, estimates the recovery and works out the statute-of-limitations date.
Capped at ask firstLitigation
Deadlines, the plan, spend against budget and the billing guideline, a recommended strategy.
Capped at ask firstMedical review
Treatment against the injury, billing anomalies and a reasonable-value range for bodily injury.
Capped at ask firstCorrespondence
The letters due on the state clocks and follow-ups for overdue diary entries, in a voice for the state.
Supervisor
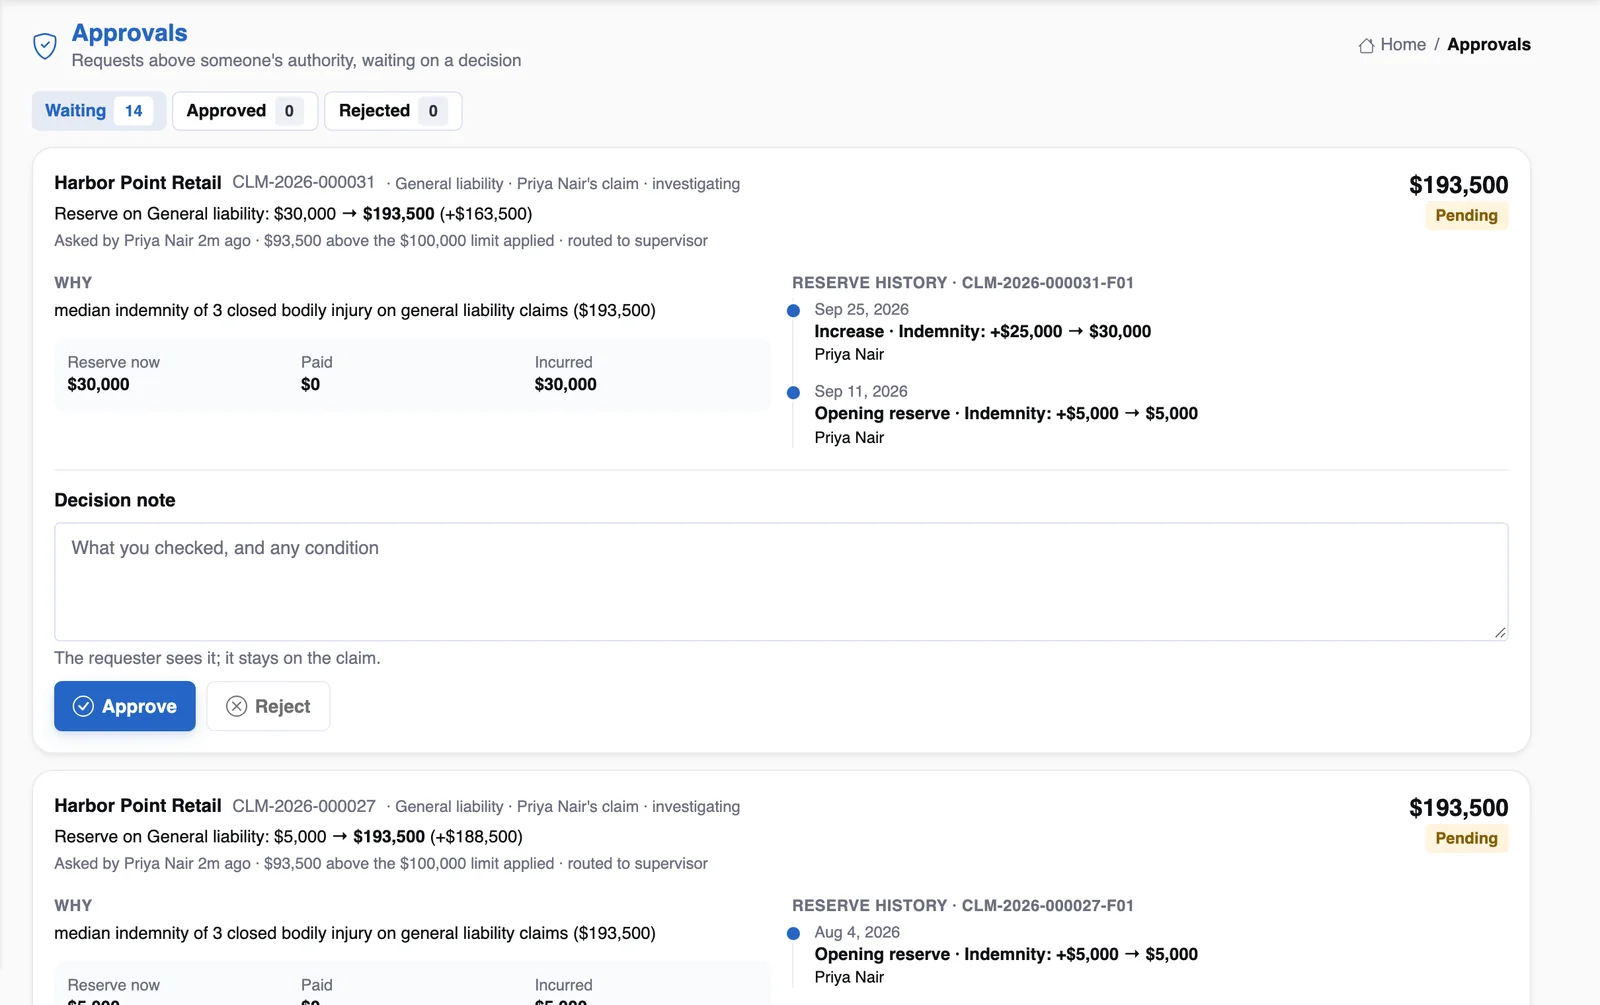
The approver’s brief: the authority gap, precedent on the line, the reserve history and the reserving agent’s figure.
Prepares approvals; never decidesClosure
Works the closing checklist and drafts the closing letter when the claim looks concluded.
A person closes a claimThe autonomy dial
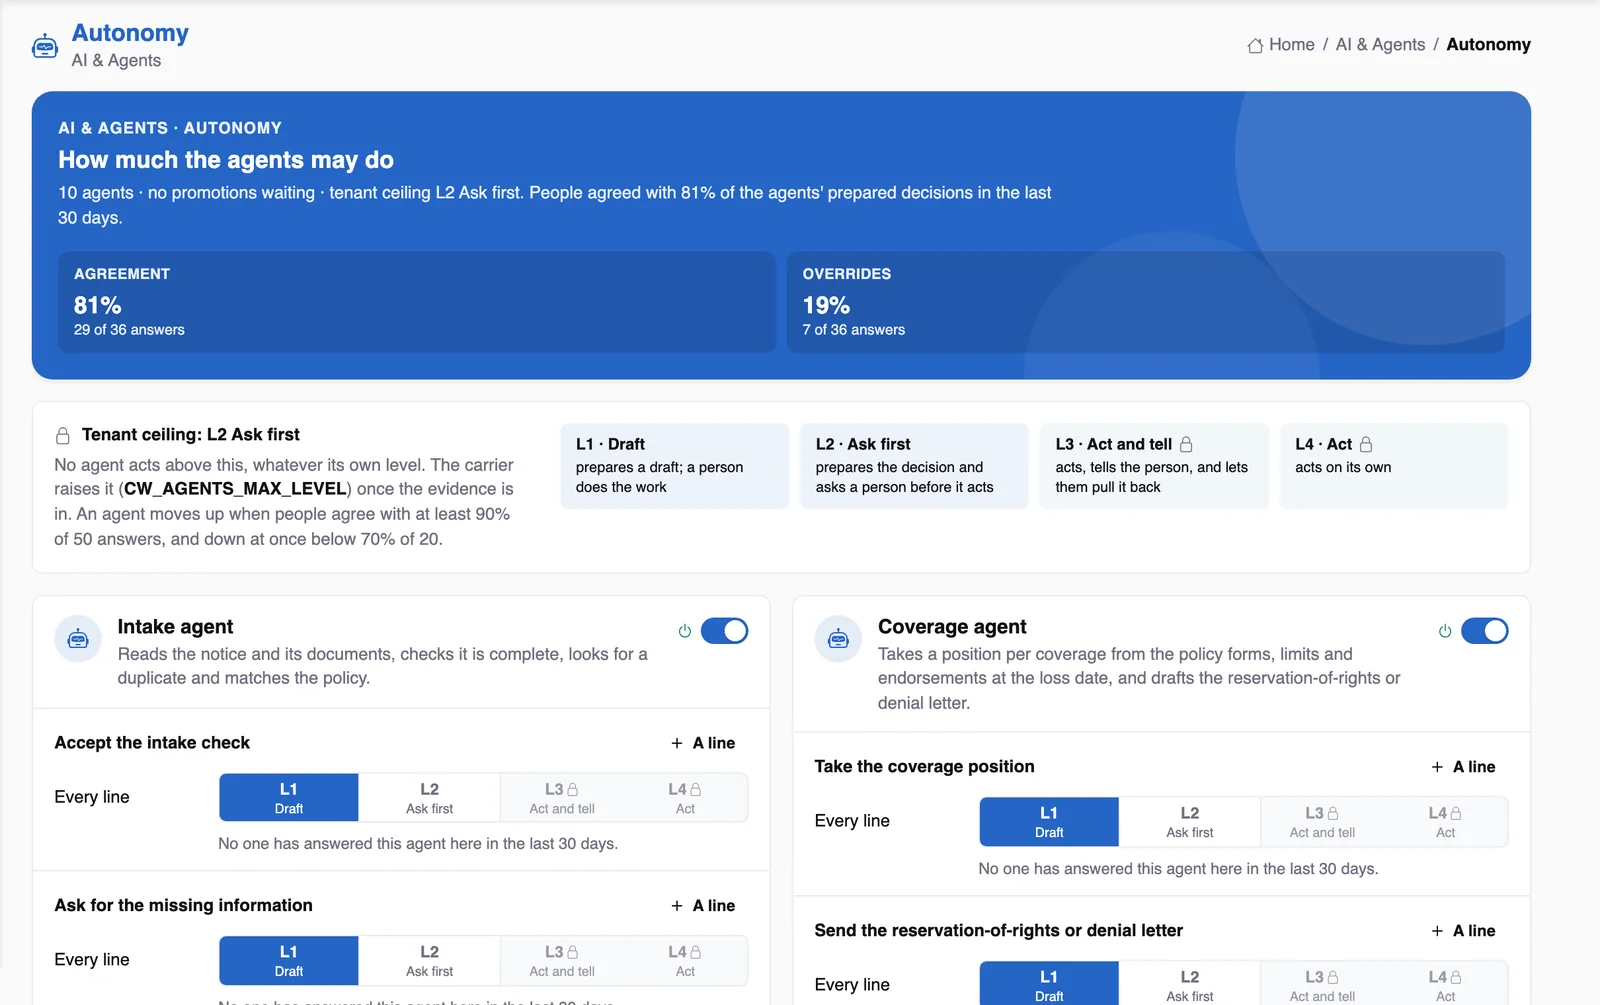
The level for any action is the lowest of three: the agent’s level for that line and action, the action’s hard cap, and the carrier’s ceiling. The ceiling ships at L2.
L1
Draft
The agent drafts; nothing is put in front of anyone. Where every agent starts.
Default ceilingL2
Ask first
The agent prepares the decision; a person with the authority accepts, changes, rejects or asks.
L3
Act and tell
Acts, tells the owner, and leaves a pull-back window to void the payment or cancel the letter.
L4
Act
Only when the carrier raises the ceiling and the evidence supports it.
Promotion is earned: an hourly roll-up recommends a notch at 90% agreement over 50 answers, which a manager accepts, and demotes at once below 70% over 20.
The claims copilot
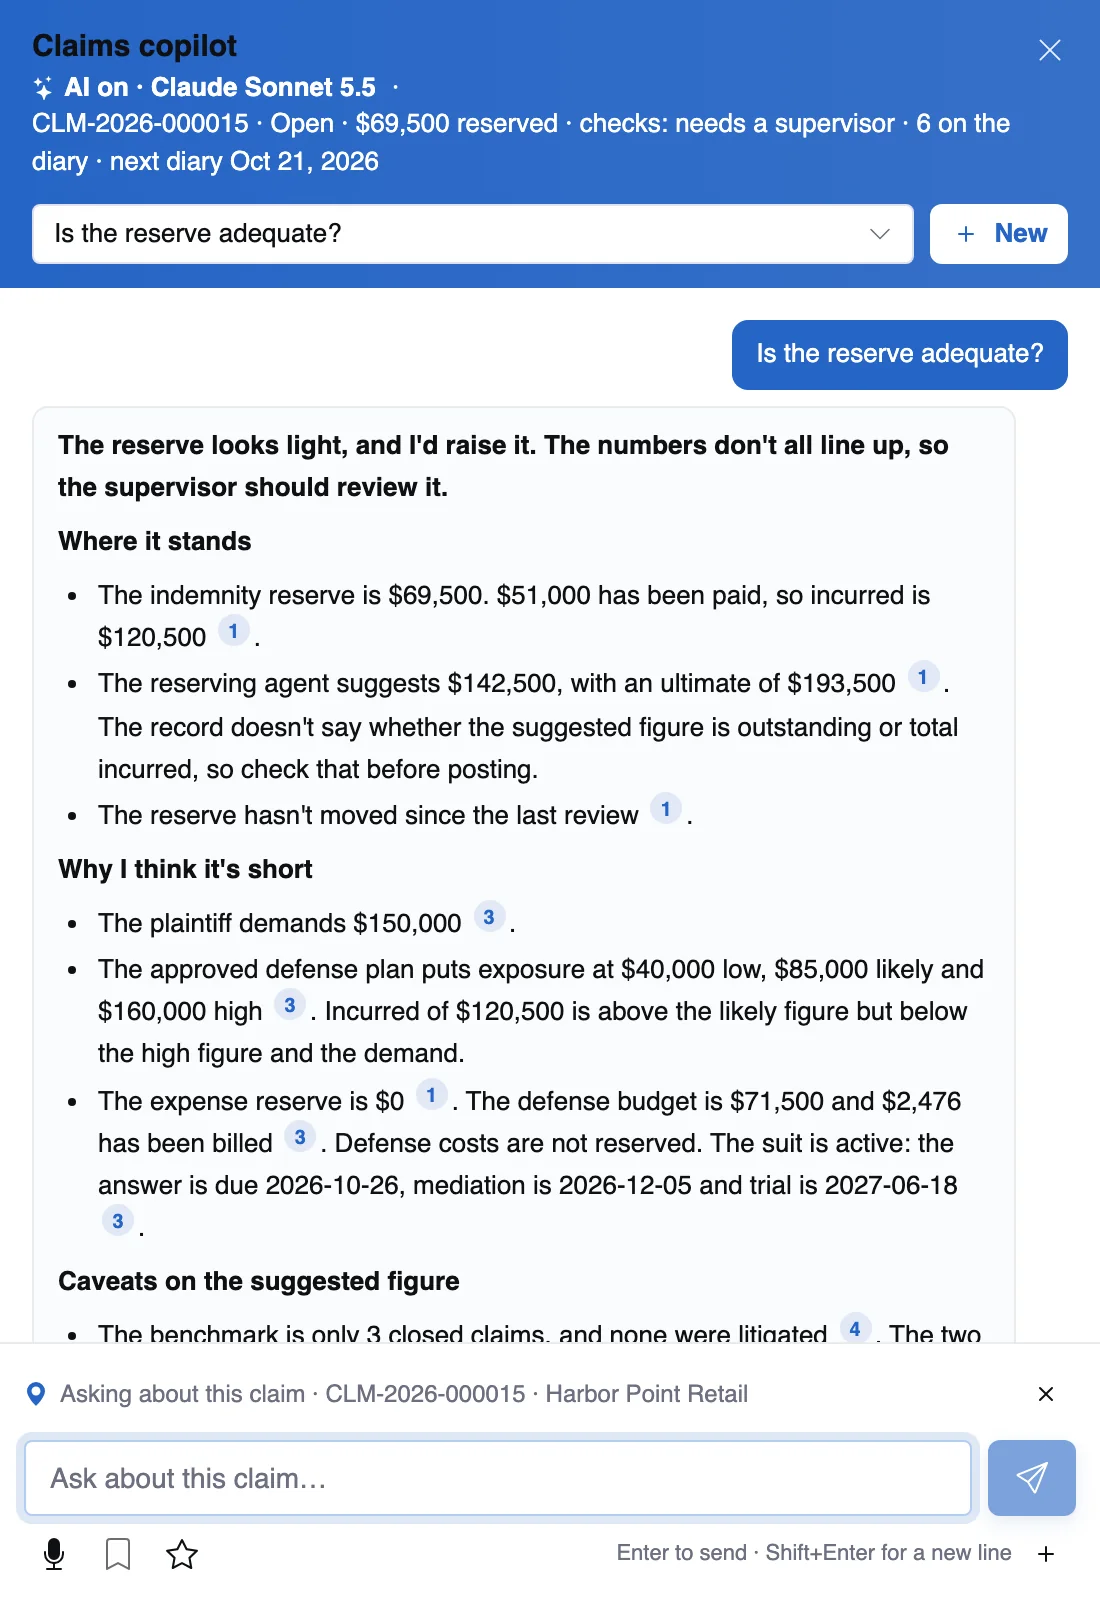
Ask the claim. Get an answer with its sources
The copilot plans, calls read-only lookups on the claim in front of you — the policy at the loss date, reserves and payments, notes, diary and clocks, documents, the decision record, litigation and recoveries, similar closed claims — and answers citing what it read.
- Every figure checked against what it read; an unsupported one is replaced with “not in the record”
- Only claims in your book; privileged notes and documents never returned
- Suggests actions as links into the workspace — it never takes them
- Claude Sonnet 5.5 by default; facts-only mode when no model is configured
Specialty lines
Each line handled the way its claims actually go
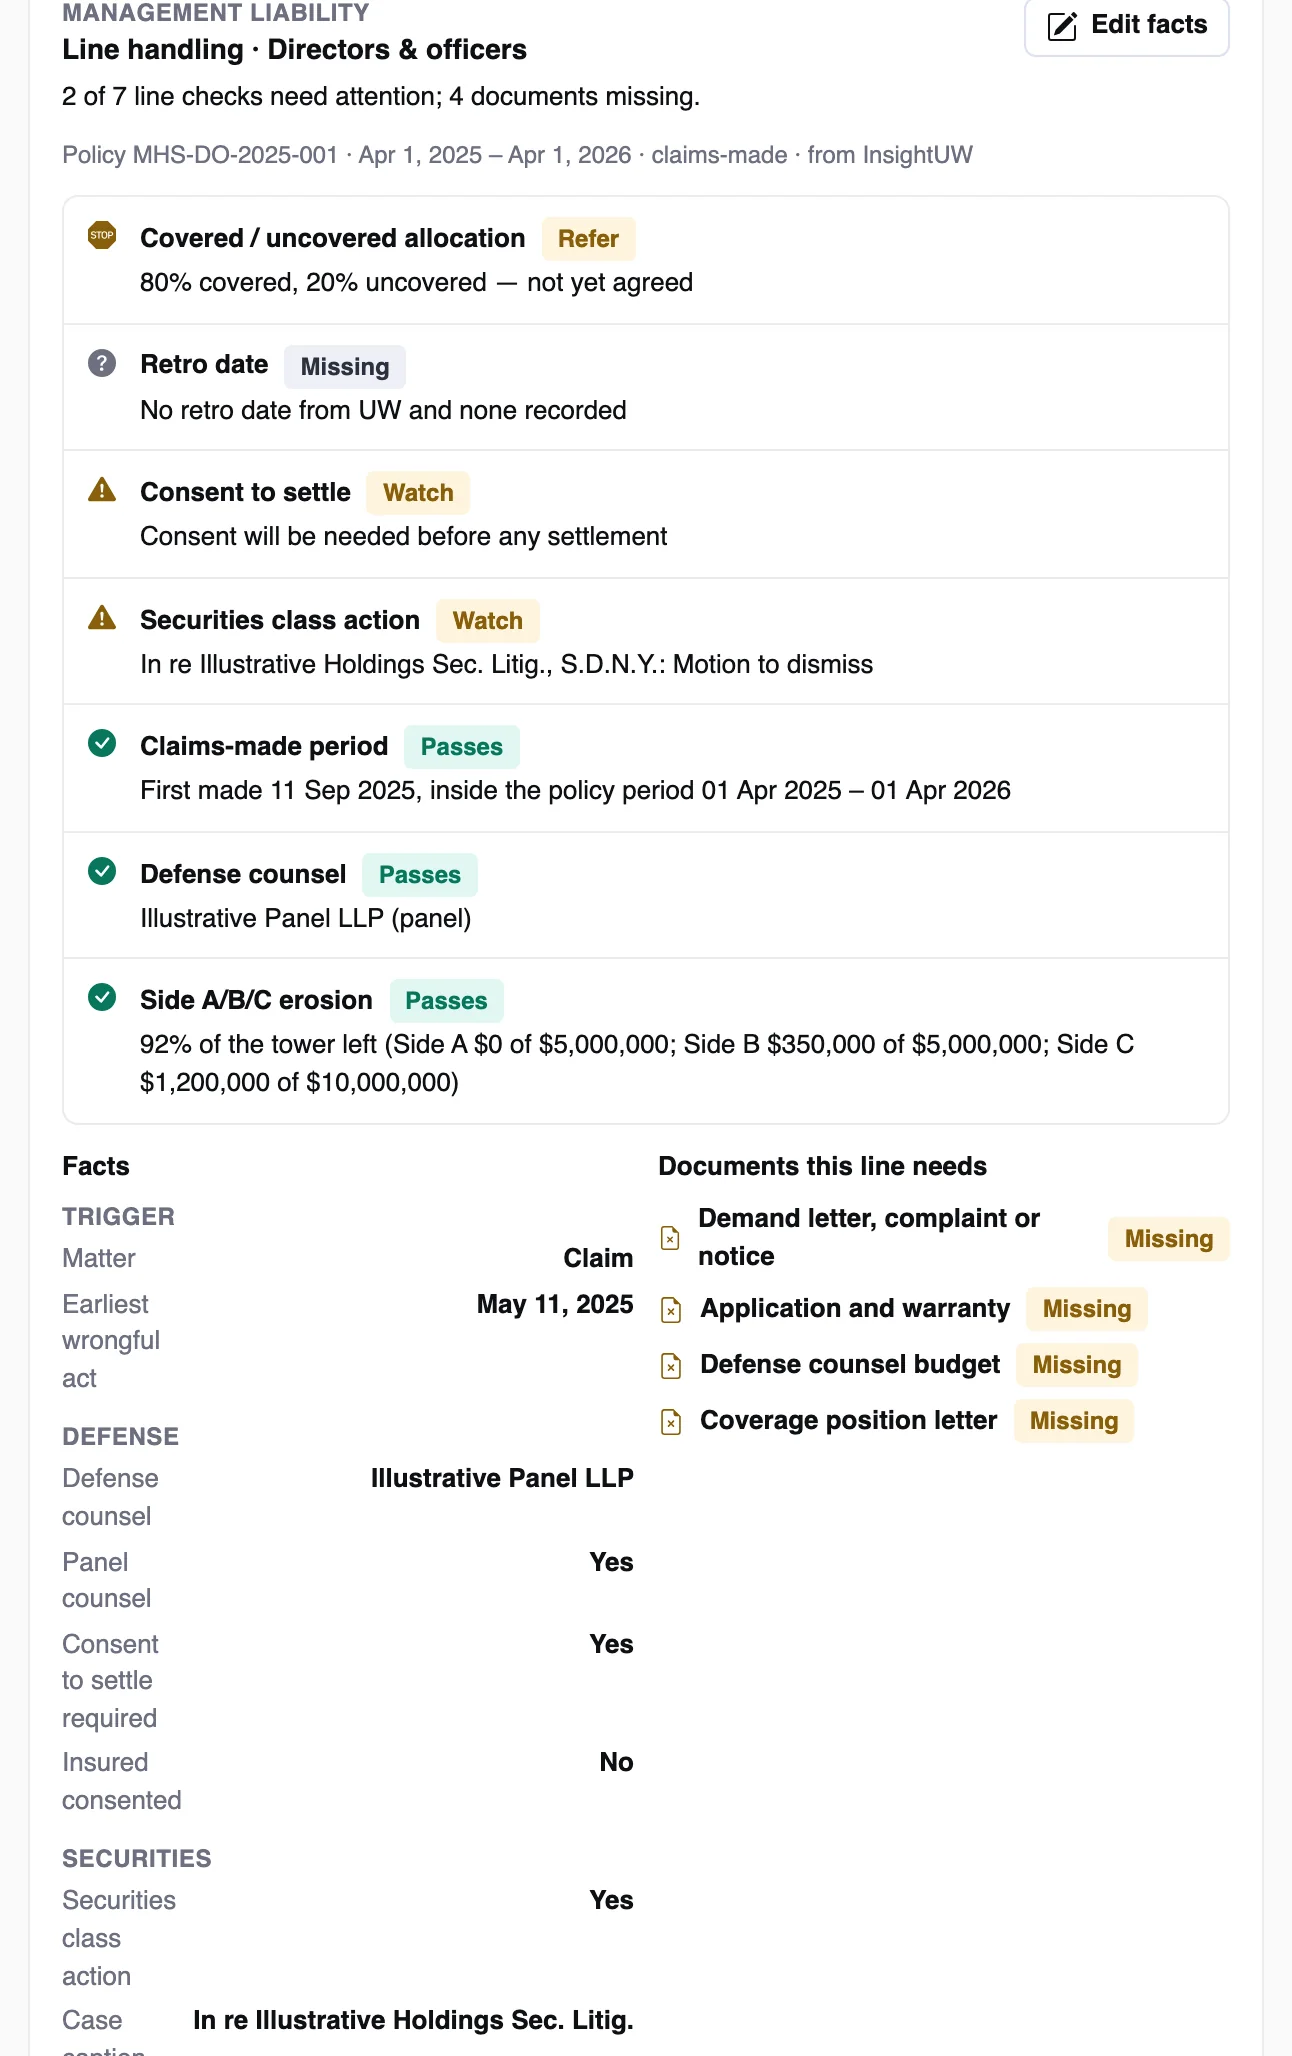
Line handling checks what matters for the line, lists the documents it needs, and opens the features and reserve components it uses. A D&O matter gets allocation, consent to settle, the claims-made period and Side A/B/C erosion; a cyber incident gets its panel vendors and notification clocks.
What the line panel does
- Line checks that pass, watch, refer or flag what is missing
- The documents the line needs, and which are on file
- Features and reserve components per line
- Claims-made trigger and retro date read from the UW policy
- Tower erosion for management liability
Fourteen lines in the catalogue across management liability, cyber, medical, marine, property, workers’ compensation and auto.
The desks
Litigation, recoveries, SIU and CAT — each with its own desk
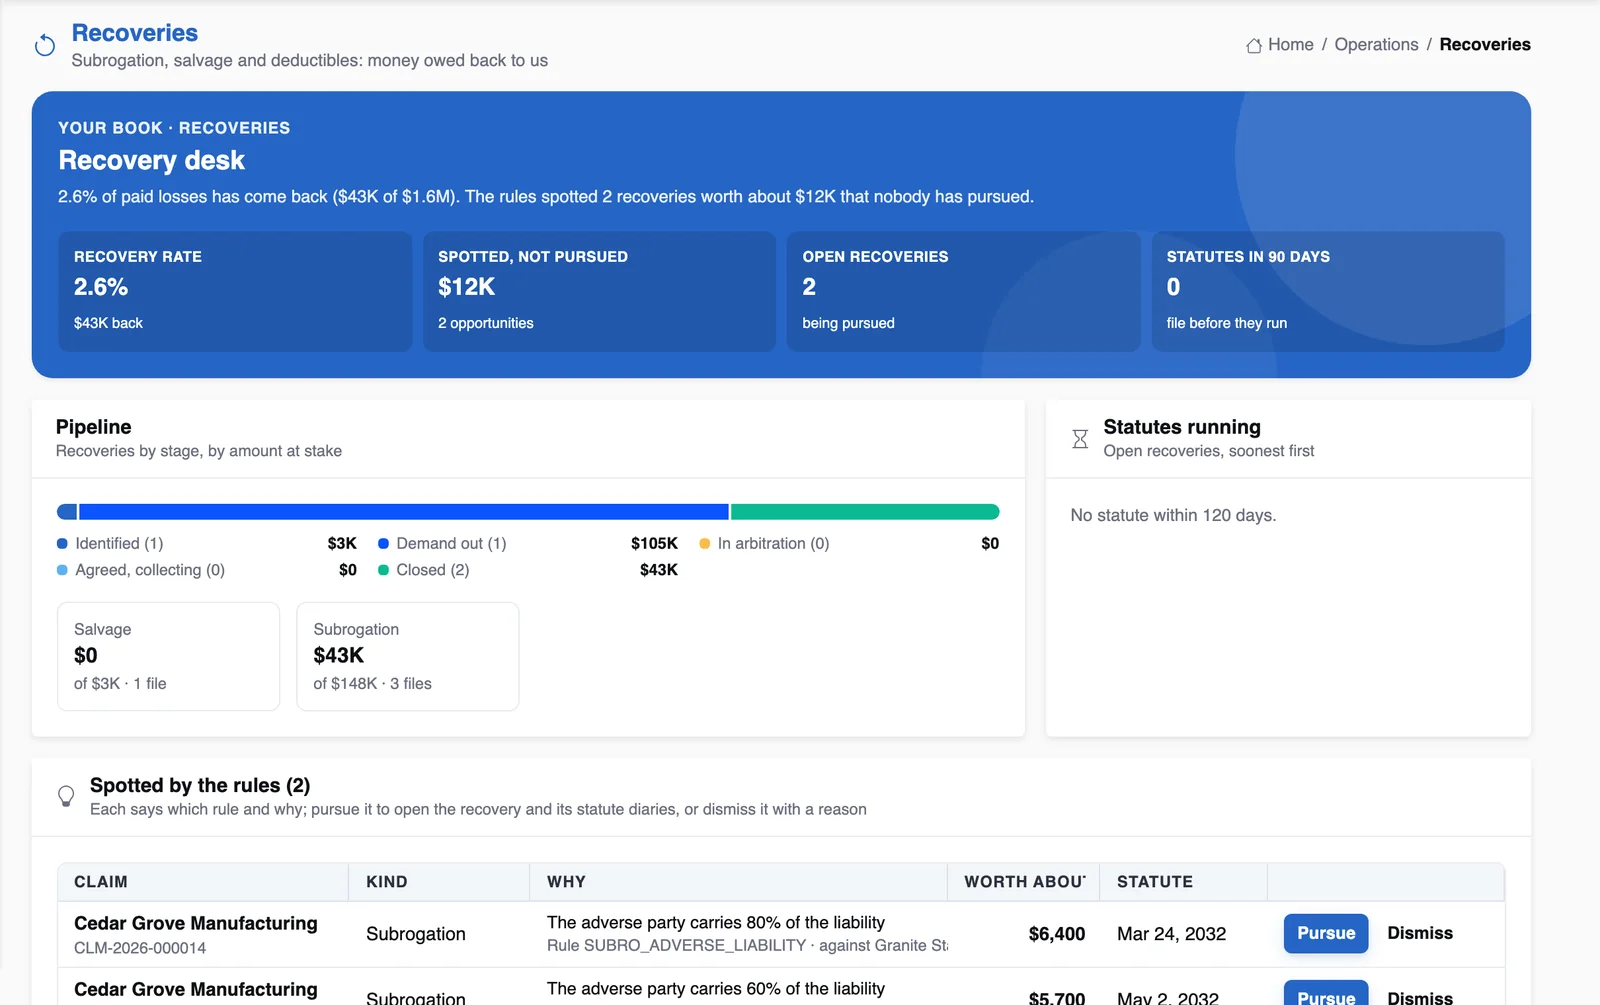
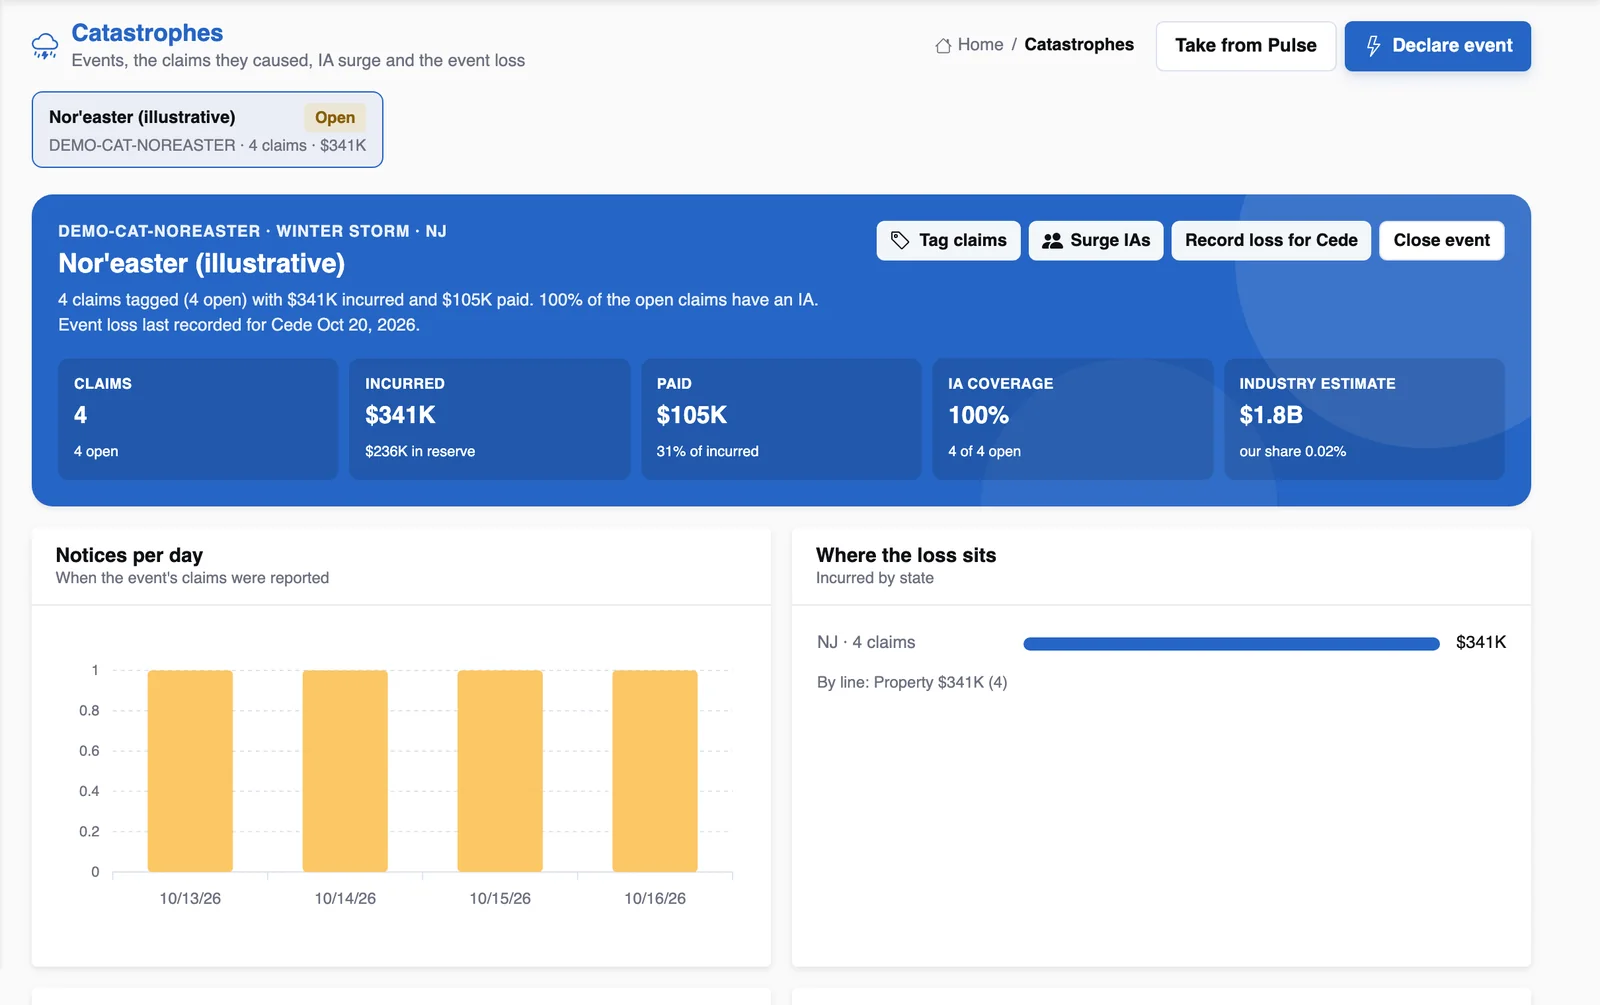
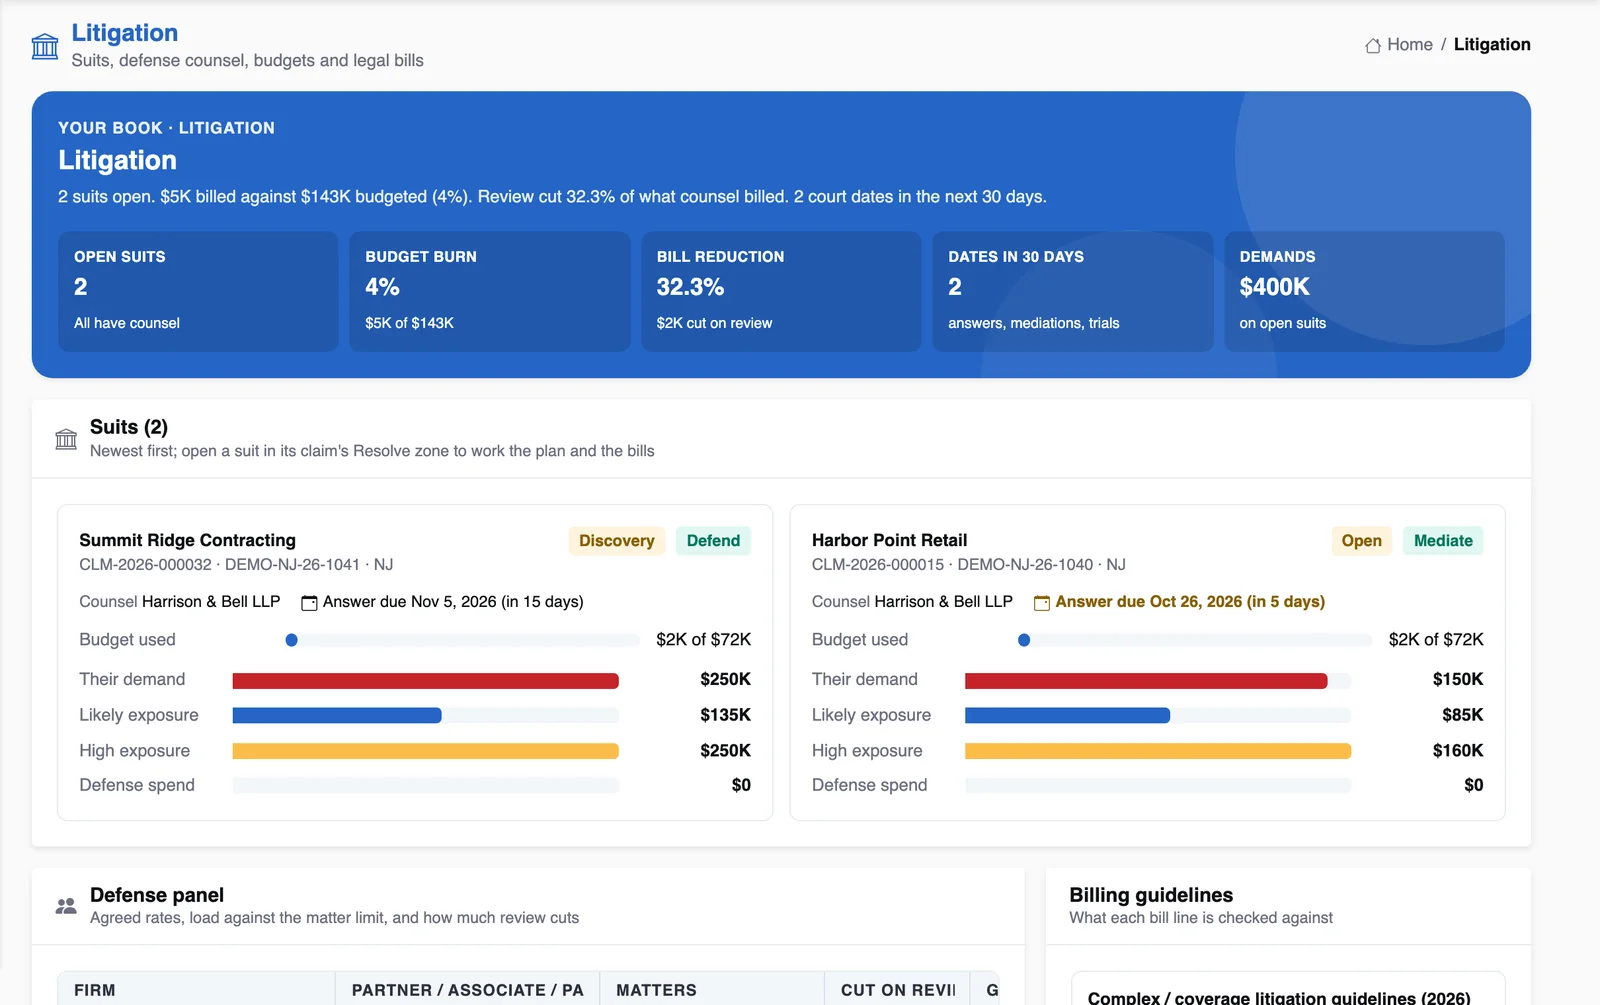
The same claims, seen from the desk that works them: suits with their plans, budgets and LEDES bills against the billing guideline; recoveries with statutes running; SIU cases; a catastrophe with its surge panel and the event loss for reinsurance.
Controls
Rules you can read, clocks you can see, payments that stop when they should
Rules Studio
Rules as sentences
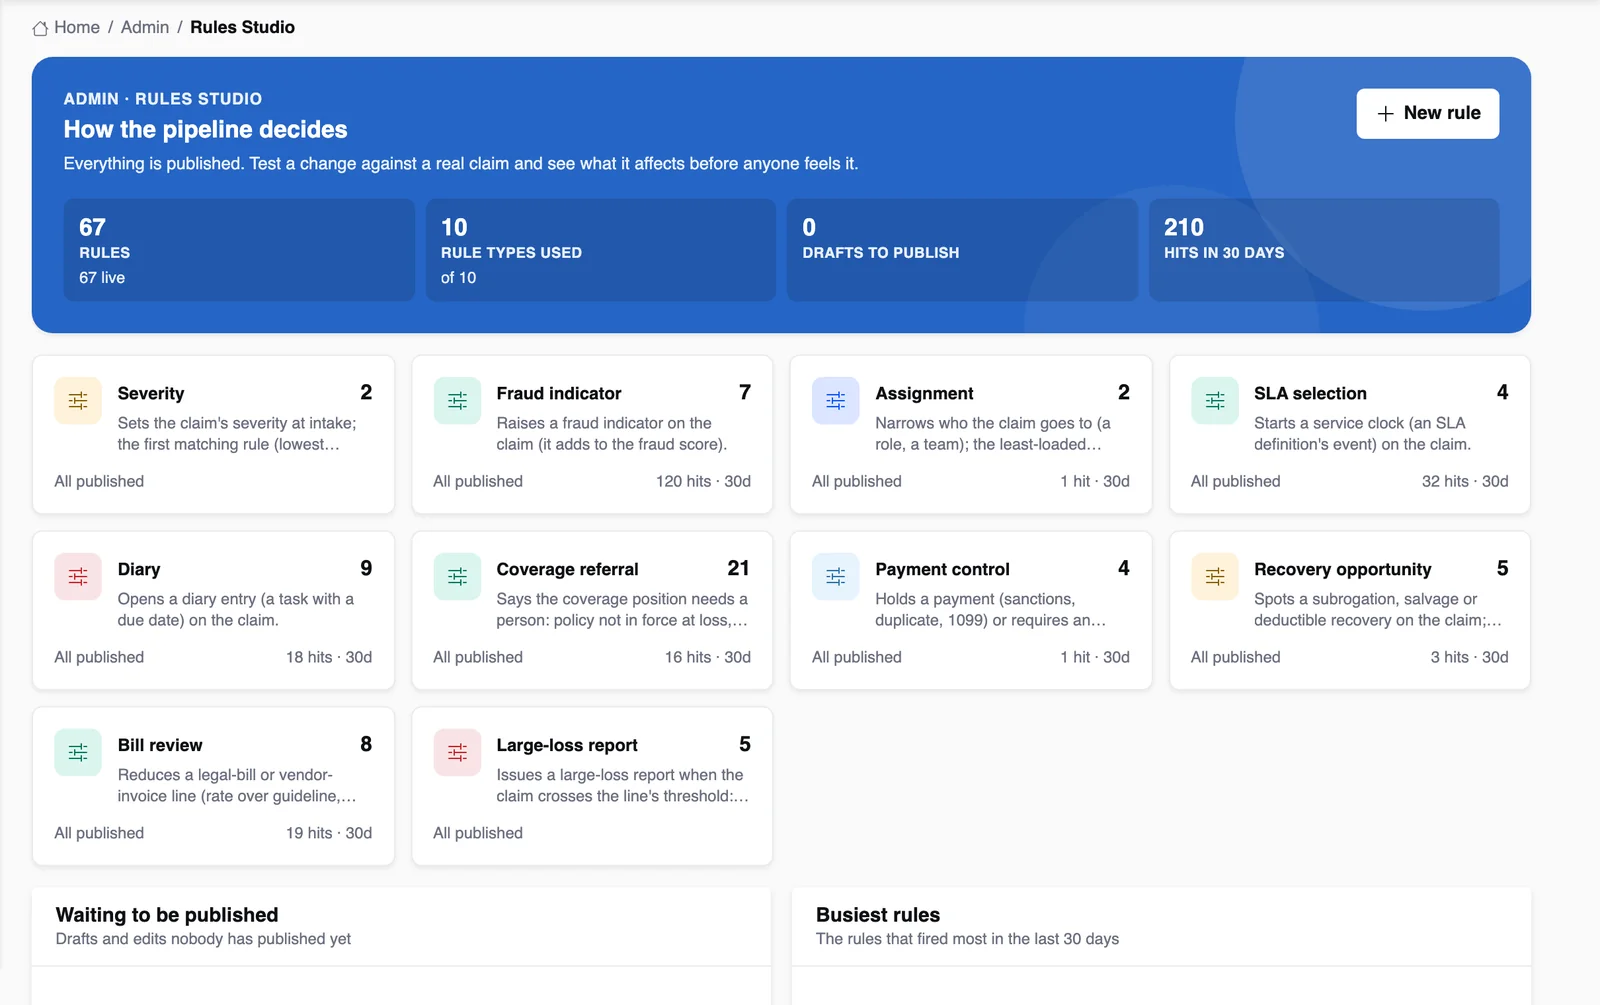
Coverage referral, fraud, severity, assignment, large loss, recovery, bill review, auto-diary, SLA and payment-control rules — written, tested against a real claim and versioned in the Studio shared with InsightUW. 67 ship in the starter set.
Payment controls
Held, not failed
Sanctions screening, duplicate payments and 1099 reporting run as rules. A payment that trips one is parked on hold with the reason, the decision record gets the hit, and a supervisor or compliance releases it.
State clocks
Deadlines on business days
Acknowledge, decide and pay clocks start and stop on claim events, on business calendars. Starter clocks for California, Florida, Illinois, New York and Texas are illustrative — each carrier confirms its own.
The connected suite
One claims record, connected to underwriting, reinsurance and the portfolio
InsightCW is the claims system of record in the Insight insurance suite. Every exchange is a signed event or a signed lookup, so each product knows exactly what the other told it.
flowchart LR
  X["InsightXtract
ACORD & loss notices"] -- "first notice, field confidence" --> CW
  UW["InsightUW
underwriting"] -- "policy & forms at the loss date (signed lookup)" --> CW["InsightCW
claims"]
  CW -- "claims experience · alerts · deductible billed" --> UW
  CW -- "cessions · voids · recoveries · CAT event loss" --> CE["InsightCede
reinsurance"]
  CW -- "claims feed" --> PU["InsightPulse
portfolio"]
InsightUW
Policy at the loss date
Limits, forms, endorsements and trigger as they stood on the loss date, not today. Claims experience and deductible bills flow back for renewal.
InsightUWInsightCede
Cessions and the CAT XoL
Every reserve and payment movement cedes on its own event; voids and recoveries come back off; a catastrophe’s event loss shows against each CAT XoL layer.
InsightPulse
The portfolio view
The claims feed merges into Pulse’s book so loss experience sits next to exposure and premium.
InsightPulseInsightXtract
Notices from documents
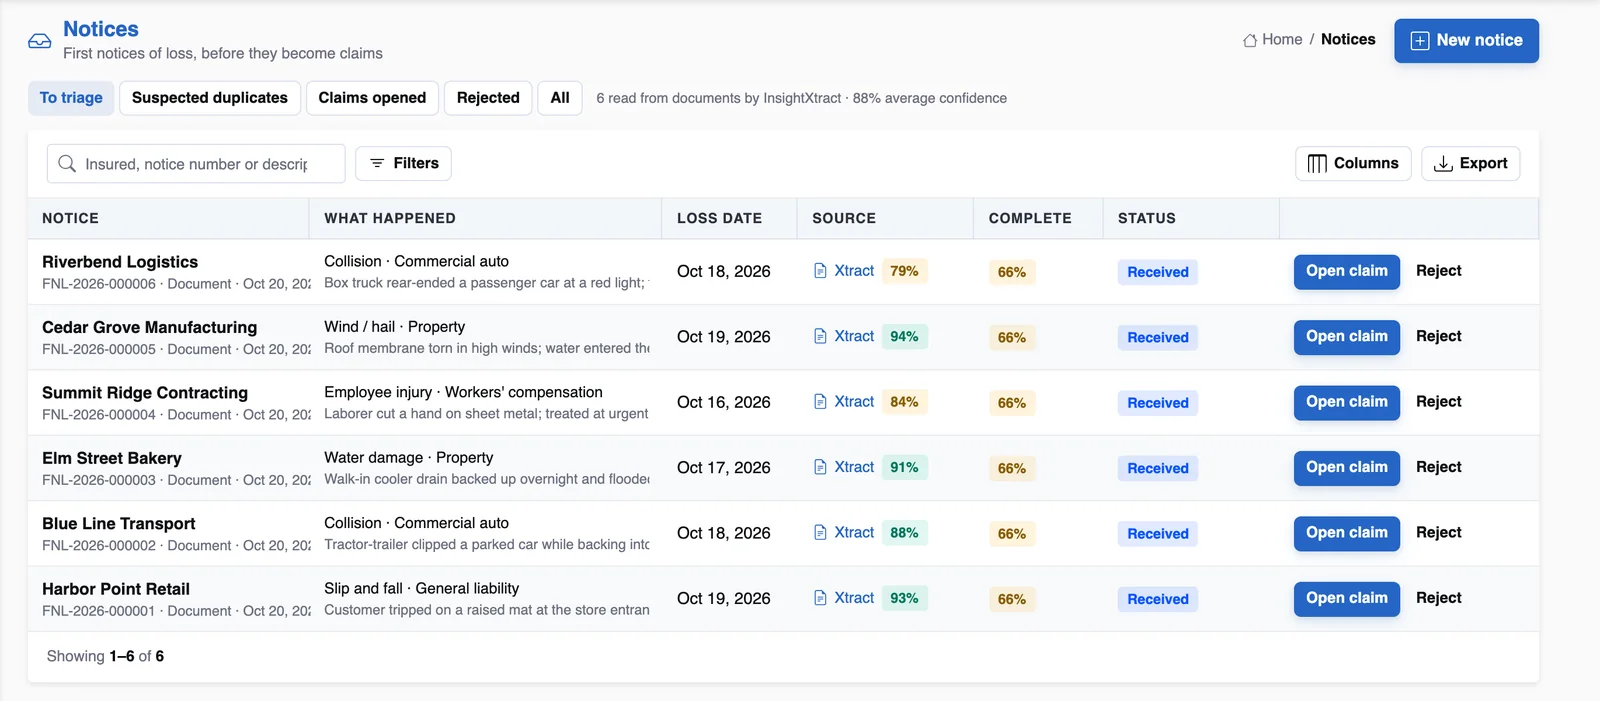
A loss notice or ACORD form read by Xtract becomes a notice with each field’s confidence and page; a person converts it to a claim.
Governance
Built so model risk and compliance can say yes
The decision record
Every run, rule hit, agent finding and person’s answer on the claim’s decision record — what was decided, by whom, on what.
Grounded figures
A model answer with a number that isn’t in the facts is thrown away and the rule-based text stands. A finding with no citation is dropped.
Scope and tenancy
Adjusters see their own book; approvers reach a claim through its approval. Every row belongs to an organization.
PII redaction
Personal data is masked before anything reaches a prompt; per-agent daily budgets and a circuit breaker on every model.
Traces and prompts
A Lense trace per agent step with model, tokens and cost; prompts versioned in InsightPrompts with local defaults.
Identity and audit
Sign-in through the Insight identity platform (OIDC), roles, API keys and an audit row for every change, including what an agent did and on whose behalf.
Deployment
Your cloud, your database, your model account
Runtime
Containers on ECS
A pinned, non-root image run as three tasks — the API, the background worker and the migration step — with a readiness check and JSON logs carrying a correlation id.
Data
PostgreSQL
One claims schema on the platform Postgres, versioned with Alembic migrations. Secrets come from the secrets manager; none live in the image.
Models
Claude on Bedrock
Claude Haiku 5.5 for agent steps and Sonnet 5.5 for the copilot, through your own AWS account. Without a model the agents fall back to their rule-based findings and say so.
Reading
Written down, claim by claim
How a claims desk works today, how the agents work inside authority, and use cases followed from first notice to close.
The docs
Getting started, and the concepts: agents, autonomy, the decision record, prepared decisions, the copilot and rules.
Read the docsUse cases
A D&O coverage question, a cyber incident, a litigated GL claim, a CAT surge, a workers’ comp medical review — end to end.
The blogWhitepapers
The operating model for an agentic claims desk, for claims leaders and model-risk owners.
Whitepapers
FAQ
What claims leaders ask first
Does an agent pay or deny a claim on its own?
No. Out of the box every agent drafts or asks first. Closing a claim, filing an SIU referral and deciding an approval are capped at ask first whatever the dial says. A carrier can raise other actions to act-and-tell, with a pull-back window, once the agreement evidence supports it.
What stops the model inventing a number?
The agents answer in a fixed shape that cites the facts they were given. Any number not in those facts throws the answer away and the rule-based finding stands, marked as such.
What does a run cost?
The trace records tokens and cost on every step. On the demo claims shown here, a full run of the ten agents cost under a cent; your volumes and lines will differ.
Do we need InsightUW?
No, but with it the coverage agent reads the policy as it stood on the loss date and claims experience flows back to underwriting. Without it, CW works from the policy it holds.